When searching for a mortgage, it’s important to do your due diligence. Not all loans are created equal!
Payday loans, as an illustration, usually carry a excessive rate of interest and an prolonged compensation interval. This may create an infinite cycle of debt that’s tough to interrupt free from.
What are they?
Loans are an integral a part of the financial system, serving to you buy a automotive or house. However in addition they carry dangers if not used with warning – notably when borrowing cash with excessive interest rates and quick compensation durations.
Luckily, there are different alternate options to payday loans. These embrace group banks, credit score unions and even native charities.
These alternate options provide decrease rates of interest, longer compensation durations and fewer threat of default. Moreover, they’re extra price-efficient than payday loans and may help you get out of debt sooner.
There are many web sites that evaluate payday loans with different borrowing choices. These websites assist you to evaluate charges and charges so you can also make an knowledgeable choice on whether or not a payday mortgage is appropriate for you.
Earlier than making use of for a payday mortgage, you should definitely analysis your state’s rules first. Some states don’t allow payday loans in any respect whereas others have stringent necessities.
When making use of for a payday mortgage, you normally want to offer proof of identification and earnings in addition to your checking account data. That is finished to verify you can repay the mortgage along with your subsequent paycheck.
Along with the quantity you borrow, you’ll additionally pay a finance price to the lender. Charges differ by state however normally quantity as both a flat price or share of whole mortgage quantity.
In 2016, The Pew Charitable Trusts reported that debtors paid a median of $55 for each $100 borrowed via payday loans – translating to an APR of practically 400%.
Payday loans can turn out to be an dependancy and go away you with a mountain of debt that’s tough to flee. They additionally put you in peril of getting into into what’s often known as a “debt spiral,” whereby you’re taking out one other mortgage with a purpose to repay the earlier one.
To keep away from payday loans altogether, search an reasonably priced different that’s extra manageable. This might contain making use of for a financial institution mortgage, taking out a private mortgage or evaluating on-line lenders.
How do they work?
Payday loans are quick-time period money advances that people borrow from lenders and repay with their subsequent paycheck. They’re standard amongst these needing fast entry to funds for payments, emergencies or different surprising prices.
To keep away from payday loans, the perfect method is both to avoid wasting up cash for emergencies or get your hands on a greater mortgage with decrease rates of interest and charges. Some choices embrace bank cards, debt administration applications and on-line lending.
One other viable choice is taking out a private mortgage out of your financial institution, which gives aggressive charges and phrases. You could possibly additionally look into installment loans for longer-time period protection with mounted month-to-month funds over an prolonged interval.
Earlier than taking out a payday mortgage, it’s clever to seek the advice of with a monetary counselor or different certified skilled. They can help in creating an achievable price range and guaranteeing you make well timed funds on the mortgage.
By no means signal a payday mortgage contract with out absolutely understanding its circumstances, reminiscent of how lengthy the mortgage will final and the way a lot you’ll owe. Moreover, you should definitely perceive what occurs when you fail to repay the mortgage in full and on time.
Most payday loans require debtors to write down a publish-dated examine for all the steadiness plus any finance prices, or give the lender authorization to electronically debit their checking account. Those that fall behind on funds may face nonsufficient funds (bounced examine) charges from their banks in addition to harassment from debt assortment businesses.
Within the worst-case situation, a lender may promote your account to a 3rd-occasion assortment company that then reviews the debt to main credit score reporting businesses. Any such adverse report can stay in your file for years and severely hurt your credit standing.
Payday loans have a tendency to hold excessive rates of interest and exorbitant APRs, making them a poor choice for a lot of customers. They can shortly spiral into debt that’s tough to flee from, plus they’re not authorized in all states.
Are they authorized?
Payday lenders present emergency money to these in monetary problem and want it shortly. Sadly, they usually cost excessive rates of interest and charges, in addition to not reporting debtors’ fee historical past to the credit score bureaus.
The federal authorities regulates payday lending to forestall customers from turning into trapped in debt traps. It additionally units disclosure necessities and enforces numerous legal guidelines towards payday lenders.
Most payday lenders are licensed within the state through which they function; nonetheless, some will not be. Examples embrace on-line lenders that get hold of a license in a single jurisdiction with permissive payday lending legal guidelines after which export this authorized framework to states with much less stringent rules.
Some payday lenders, notably these positioned on Native American tribal lands, declare immunity from go well with below sovereign immunity legal guidelines. Because of this, they might cost exorbitant rates of interest and function exterior the legislation.
One other potential challenge is that payday lenders can seize your cash even when you haven’t been sued. That is notably true if there may be cash in your checking account from direct-deposited social safety or the Veteran’s Administration (VA), that are exempt from garnishment.
Moreover, many payday lenders will take your checking account and debit it for the complete mortgage quantity plus finance prices. This implies when you don’t pay again the mortgage on time, banks may cost wherever from $25-$35 in penalties.
In case you’re unsure if a payday mortgage is authorized, seek the advice of an legal professional. The Choose Advocate Normal’s (JAG) Authorized Help Workplace locator may help find an legal professional in your space.
If you don’t want to proceed with the mortgage, you may have the correct to rescind it. In such case, the lender should return any postdated checks or cancel any digital withdrawals out of your checking account.
Chances are you’ll file a grievance with the Federal Commerce Fee (FTC) and your state legal professional basic. The FTC has taken a number of legislation enforcement actions towards payday lenders, together with misleading and unfair promoting, violation of the Fact in Lending Act, wage task clauses in contracts, pre-authorization for digital fund transfers and different abusive practices.
Are they harmful?
Are you unsure whether or not loans payday are harmful? You is perhaps happy to know they’re not as dangerous as one may suppose. In truth, they will usually be an advantageous answer for these with bad credit report and quick-time period monetary wants.
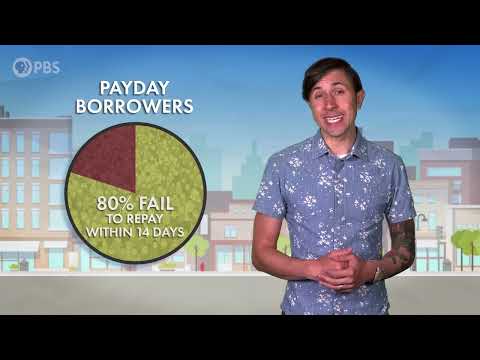
The first disadvantage to payday loans is that they usually turn out to be a vicious debt cycle that’s tough to flee. Moreover, these loans are extraordinarily costly and necessitate a considerable quantity of funds with a purpose to be repaid.
Most debtors take out payday loans to fill a short lived budgetary gap, both for an emergency or to cowl payments till their subsequent paycheck arrives. Sadly, many of those debtors turn out to be trapped in a debt cycle the place they both want to increase or roll over their present mortgage or take out one other one.
This cycle might be way more difficult to interrupt than you suppose, because it’s virtually at all times not possible to foretell when you should have sufficient cash for compensation in full. Moreover, many payday lenders cost an extension price every time you lengthen your mortgage – additional rising out-of-pocket bills.
Sadly, many debtors maintain taking out payday loans till they’ve constructed up an amazing debt load, making it practically not possible to flee the cycle. The one manner out is discovering a technique to repay each your payday mortgage and any related charges or curiosity that include them.
In case you’re unable to pay again the mortgage, payday lenders could try and ship it off for collections – which may harm your credit score. They even have authorized avenues out there reminiscent of submitting a lawsuit in court docket to gather what’s owed.
Even when your mortgage doesn’t go to collections, it can nonetheless seem in your credit score report and probably make it tougher so that you can get hold of bank cards or mortgages sooner or later. Moreover, in lots of instances, your credit score rating could drop a couple of factors on account of these actions.
In case you’re having bother affording a payday mortgage, different debt options like borrowing from family and friends or discovering an extra job that pays shortly could also be out there. These different debt options may help forestall falling into an infinite cycle of payday mortgage debt.